Las Vegas Housing Market Trends & Forecast through 2030

Las Vegas Housing Market Trends & Forecast through 2030

Las Vegas Housing Market

2026 marked a noticeable shift in the Las Vegas housing market. Buyer demand became more selective as higher mortgage rates reduced affordability, while more homes remained available for sale and sellers faced greater competition.

That change showed up clearly in the numbers. Single-family inventory increased from approximately 6,850 homes in March to about 8,400 by fall. Monthly sales reached roughly 2,100 homes during the spring before declining to approximately 1,730 later in the year. Over the same period, available housing supply increased from about 3.35 months to 4.85 months.

Mortgage rates were an important part of the shift. Higher financing costs increased monthly payments and reduced how much home many buyers could comfortably afford. As rates remained elevated during 2026, buyers became more price-sensitive, took longer to make decisions, widened their search, or stepped away from the market altogether.

For sellers, that created a different transaction environment. Buyers had more homes to compare and more leverage to negotiate on price, repairs, closing costs, mortgage-rate buydowns, and other concessions. Sellers also faced greater pressure to reduce asking prices when the market or an appraisal did not support their original expectations.

Mortgage rates remained a major affordability constraint in 2026. Mortgage News Daily reported a top-tier 30-year fixed mortgage rate of 7.54% on October 1, 2026. At rates in this range, monthly payments were substantially higher than during the low-rate pandemic years, limiting purchasing power even for buyers whose incomes had increased. View Mortgage News Daily rate data .

Seller concessions became increasingly common as the market shifted. By late summer 2026, Redfin reported that 66.7% of Las Vegas-area home sales in its sample included some form of seller concession. Price reductions were measured separately, meaning some sellers were reducing their asking price and still contributing additional money toward closing costs, repairs, or financing incentives.

Selling was also taking longer. In our local experience, the full timeline from the original listing date through the actual closing was approaching roughly four months in some transactions. That is different from traditional days-on-market statistics and more closely reflects how long a homeowner may be carrying the property before receiving the sale proceeds.

Some homeowners who do not need to sell immediately are choosing another path. Rather than continue reducing the price, they may withdraw the home from the market, wait, or consider renting it instead. Owners with low mortgage rates, significant equity, cash purchases, or adequate reserves often have more flexibility to make that decision.

That financial flexibility is one reason the Las Vegas market has remained relatively resilient. More inventory, longer selling times, and greater negotiation do not automatically mean widespread housing distress when many owners still have the ability to hold rather than sell under pressure.

2026 Market Shift

Higher financing costs slowed buyer demand while housing inventory continued to build.

6,850 → 8,400 Approximate increase in active single-family inventory from March through fall 2026
2,100 → 1,730 Approximate decline in monthly single-family sales from the spring peak to later in 2026
3.35 → 4.85 months Increase in available housing supply as buyer demand slowed

The 2026 Las Vegas housing market was not experiencing widespread distress. It was becoming slower, more balanced, and more negotiable. Elevated mortgage rates constrained purchasing power, inventory increased, homes took longer to sell, and buyers gained more leverage, but financially stable homeowners and limited forced selling continued to provide support for the market.

How Did the Las Vegas Housing Market Shift in 2026?

The most important change in 2026 was a gradual shift in negotiating power. Higher mortgage rates reduced affordability, more homes became available for sale, and buyers had more time to compare their options before making an offer.

What Did Rising Housing Inventory Mean?

During 2026, single-family housing inventory increased from approximately 6,850 homes in March to about 8,400 by fall. Over the same period, monthly sales slowed from roughly 2,100 homes during the spring to approximately 1,730 later in the year.

Available housing supply increased from approximately 3.35 months to 4.85 months. Months of inventory estimates how long it would take to sell the homes currently available if no additional properties were listed and sales continued at the same pace.

Under 4 Months Generally leans toward sellers because available supply remains relatively limited.
4 to 5 Months Generally represents a more balanced relationship between buyers and sellers.
6 Months or More Generally provides buyers with greater selection and negotiating leverage.

By fall 2026, Las Vegas remained near a broadly balanced level of supply by this measure. The more important change was that buyers had more alternatives while sellers faced more competition than they had earlier in the year.

Negotiations Became More Important

Buyers were touring more homes, comparing properties more carefully, and taking longer to decide whether to write an offer. That gave them more room to negotiate on price, repairs, closing costs, financing incentives, and other terms.

Rice Real Estate & Property Management saw this firsthand. In one transaction, a home originally listed at approximately $425,000 was reduced to approximately $405,000, and the seller still contributed about $10,000 toward the buyer's closing costs.

On some higher-priced homes, we also saw asking-price reductions of $100,000 or more. These are individual transaction examples rather than valley-wide averages, but they illustrate how much more important negotiation became as buyers gained additional choices.

Appraisals Became More Important in Negotiations

Appraisals also became more consequential as buyers gained alternatives. When a property did not appraise at the contract price, buyers were less likely to feel pressure to make up the difference themselves.

If a seller was unwilling to reduce the price to a level supported by the appraisal, some buyers were willing to walk away and continue shopping. That was a meaningful change from tighter seller-market conditions, when buyers often felt they had fewer alternatives.

Selling a Home Was Taking Longer

Traditional days-on-market statistics do not always show homeowners how long the entire selling process may take. A seller must first secure an acceptable buyer and then complete inspections, appraisal, financing, and escrow before receiving the sale proceeds.

In our local experience during 2026, the full timeline from the original listing date through the actual closing was approaching roughly four months in some Las Vegas transactions.

That is a different measurement from MLS days on market, but it can be more useful for homeowners trying to plan around carrying costs, relocation, another home purchase, or the timing of their sale proceeds.

Some Sellers Chose to Wait Rather Than Sell

Not every homeowner had to accept the terms buyers were offering. Sellers with low mortgage rates, substantial equity, homes purchased with cash, or sufficient financial reserves sometimes had the option to wait rather than continue reducing the price.

Rice Real Estate & Property Management began seeing some homeowners withdraw their properties from the sales market and either hold the home or consider renting it instead.

That distinction matters. A homeowner voluntarily choosing not to sell is very different from a homeowner being forced to sell because of financial distress. More inventory, longer selling times, price reductions, and seller concessions can indicate a more buyer-friendly market without indicating a housing crash.

Advice Is Always Free
Learn more about professional property management services.
Image link

What Did the 2026 Market Shift Mean for Buyers, Sellers, and Homeowners?

For Buyers

More Time to Compare and Negotiate

Buyers had more homes to choose from and more time to compare properties before writing offers. That created more room to negotiate on price, repairs, seller contributions, and appraisal issues.

For Sellers

Price Was Only Part of the Negotiation

Sellers increasingly had to prepare for a longer process and recognize that a price reduction might not be the final concession. Accurate pricing, property condition, closing costs, repairs, and appraisal results all became more important.

For Homeowners

Selling Was Not Always the Only Option

Homeowners who did not need to sell immediately often had more flexibility. Depending on mortgage costs, equity, reserves, rental value, and long-term plans, holding or renting the home became another option to evaluate.

For Investors

More Time to Evaluate Opportunities

Rising inventory gave investors more time to compare properties and negotiate. A lower purchase price still needed to be supported by realistic rent, financing, taxes, insurance, HOA costs, maintenance, and expected vacancy.

A Better Way to Manage a Las Vegas Rental
Rice Real Estate & Property Management

Las Vegas Housing Market Forecast Through 2030

The Las Vegas housing market appears to be entering a slower period, but it has also proven resilient. More homes are available for sale, buyers are taking longer to make decisions, and sellers are negotiating more than they did during the strongest seller-market years. What we are not seeing is widespread forced selling or the type of financial distress that typically creates rapid downward pressure on home prices.

Looking ahead to 2030, Las Vegas may simply be moving into an environment where selling a home requires more patience, realistic pricing, and a greater willingness to negotiate.

Our Las Vegas Housing Market Outlook Through 2030

  • Las Vegas is likely to remain a functioning but slower housing market rather than returning quickly to the unusually fast sales environment of the pandemic years.
  • Sellers who price realistically, maintain the property well, and allow four to six months for the complete selling process should still have a reasonable path to a successful sale.
  • Buyers should continue to have more time to compare homes and negotiate on price, repairs, closing costs, financing incentives, and other terms.
  • Mortgage rates will remain one of the strongest influences on transaction volume and affordability.
  • A meaningful decline in mortgage rates could bring sidelined buyers back into the market and increase sales activity.
  • Home prices may move differently by neighborhood, price range, property condition, and housing type rather than rising or falling uniformly across the Las Vegas Valley.
  • Well-priced and well-presented homes should continue to outperform homes priced according to older seller expectations.

Why Has the Las Vegas Housing Market Remained So Resilient?

Many existing homeowners are not under immediate pressure to sell. A large number purchased or refinanced during the exceptionally low-interest-rate years surrounding the pandemic and may be reluctant to give up a mortgage payment that would be difficult to replace today.

Other properties are owned with substantial equity, were purchased with cash, or are held as investments. Some homeowners also have enough financial flexibility to carry two properties temporarily while deciding whether to sell, hold, or rent the first home. That flexibility can reduce the number of owners who must accept an unfavorable sale simply because they need to exit the property immediately.

Together, these factors help explain why increasing inventory and longer selling times have not automatically translated into widespread distressed pricing.

Mortgage Rates May Determine How Quickly Sales Activity Improves

Mortgage rates remain one of the biggest obstacles to a faster Las Vegas housing market because they affect both buyers and existing homeowners.

Buyers face higher monthly payments and reduced purchasing power. Existing homeowners may postpone selling because moving could mean replacing a low-rate mortgage with a substantially more expensive loan.

If mortgage rates decline meaningfully between now and 2030, Las Vegas could see sales volume improve before there is a dramatic change in home prices. Buyers who have been waiting for a more affordable payment may return, while some homeowners who have felt locked into existing mortgages may become more willing to move.

A Four-to-Six-Month Selling Timeline May Become More Normal

During the strongest seller-market years, homeowners became accustomed to homes selling very quickly. A healthier but slower market can look different. Marketing the property, securing the right buyer, negotiating repairs or concessions, completing an appraisal, obtaining financing, and closing escrow can take several months.

Based on what we are seeing locally, homeowners who are financially able to allow approximately four to six months from the initial listing through an eventual closing may be better positioned than sellers who need an immediate sale.

That does not mean every home will require six months to sell. An accurately priced, well-maintained home in a desirable location can move considerably faster.

Sellers May Need to Give Buyers More Than a Lower Price

Seller concessions are likely to remain important while mortgage rates remain elevated. Buyers are often as concerned with monthly payment and cash required at closing as they are with the asking price itself.

A seller may therefore have more success helping with closing costs or a mortgage-rate buydown rather than relying exclusively on repeated price reductions. Property condition will matter as well. When buyers have several comparable homes available, they have less reason to accept deferred maintenance, dated condition, appraisal concerns, or an aggressive asking price without receiving something in return.

What We Expect Through 2030

Our outlook is for Las Vegas to remain a healthy but more selective housing market through the end of the decade. We do not expect every year or every neighborhood to perform the same way, and periods of flat or modestly declining prices are possible when affordability becomes strained.

If mortgage rates gradually improve while employment and household formation remain reasonably stable, sales activity could strengthen without requiring a major correction in home values. If rates remain elevated, the more likely outcome may be a continuation of the slower market that began developing in 2026: more inventory, longer selling timelines, more negotiation, and greater differences between homes that are positioned correctly and those that are not.

Rice Real Estate & Property Management's perspective: The Las Vegas housing market does not currently look unhealthy. It looks slower. Sellers may need more patience and buyers have more leverage, but homeowners with realistic expectations can still sell successfully. The biggest adjustment may be accepting that a normal sale can take months rather than weeks.

Is the Las Vegas Housing Market Going to Crash?

The 2026 data shows a slower and increasingly buyer-friendly Las Vegas housing market, but current conditions do not resemble the type of extreme oversupply or widespread financial distress normally associated with a housing crash.

Available single-family inventory increased during 2026, while sales slowed and buyers gained more negotiating leverage. By fall, months of available inventory had increased to approximately 4.85 months, a level that still falls close to what is generally considered a balanced market.

What has changed is the amount of competition among sellers. Buyers have more properties to choose from, are taking longer to make decisions, and are negotiating more on price, closing costs, repairs, financing incentives, and appraisal issues.

Longer selling timelines, price reductions, seller concessions, and more appraisal-related negotiations are signs of a softer and more selective market. They are not, by themselves, evidence of widespread housing distress.

One reason the Las Vegas market has remained relatively resilient is the financial position of many property owners. Low-rate mortgages, substantial equity, cash ownership, and the ability of some homeowners to hold or rent rather than sell reduce the number of owners who must accept an unfavorable sale simply because they need to exit immediately.

That is very different from a market dominated by forced sellers. A homeowner who can wait, withdraw a listing, or convert a property to a rental is in a different financial position from an owner facing foreclosure or another forced-sale situation.

A distressed housing market would generally look different. A repeat of the Great Recession would likely require a much more serious combination of forced sales, rising foreclosures, widespread financial distress, collapsing demand, and substantially more housing supply than the market can absorb.

That does not mean Las Vegas home prices cannot decline. Individual neighborhoods, price ranges, or property types can experience meaningful price reductions even when the broader market remains financially healthy. Sellers competing against numerous similar homes may also face more pricing pressure than valley-wide averages suggest.

The Las Vegas housing market does not currently look distressed. It looks slower. Buyers have more leverage, sellers may need more time and greater flexibility on price or concessions, and some homes may take months rather than weeks to sell. The key difference is that many property owners still have the financial ability to wait, hold, or rent rather than being forced to sell.
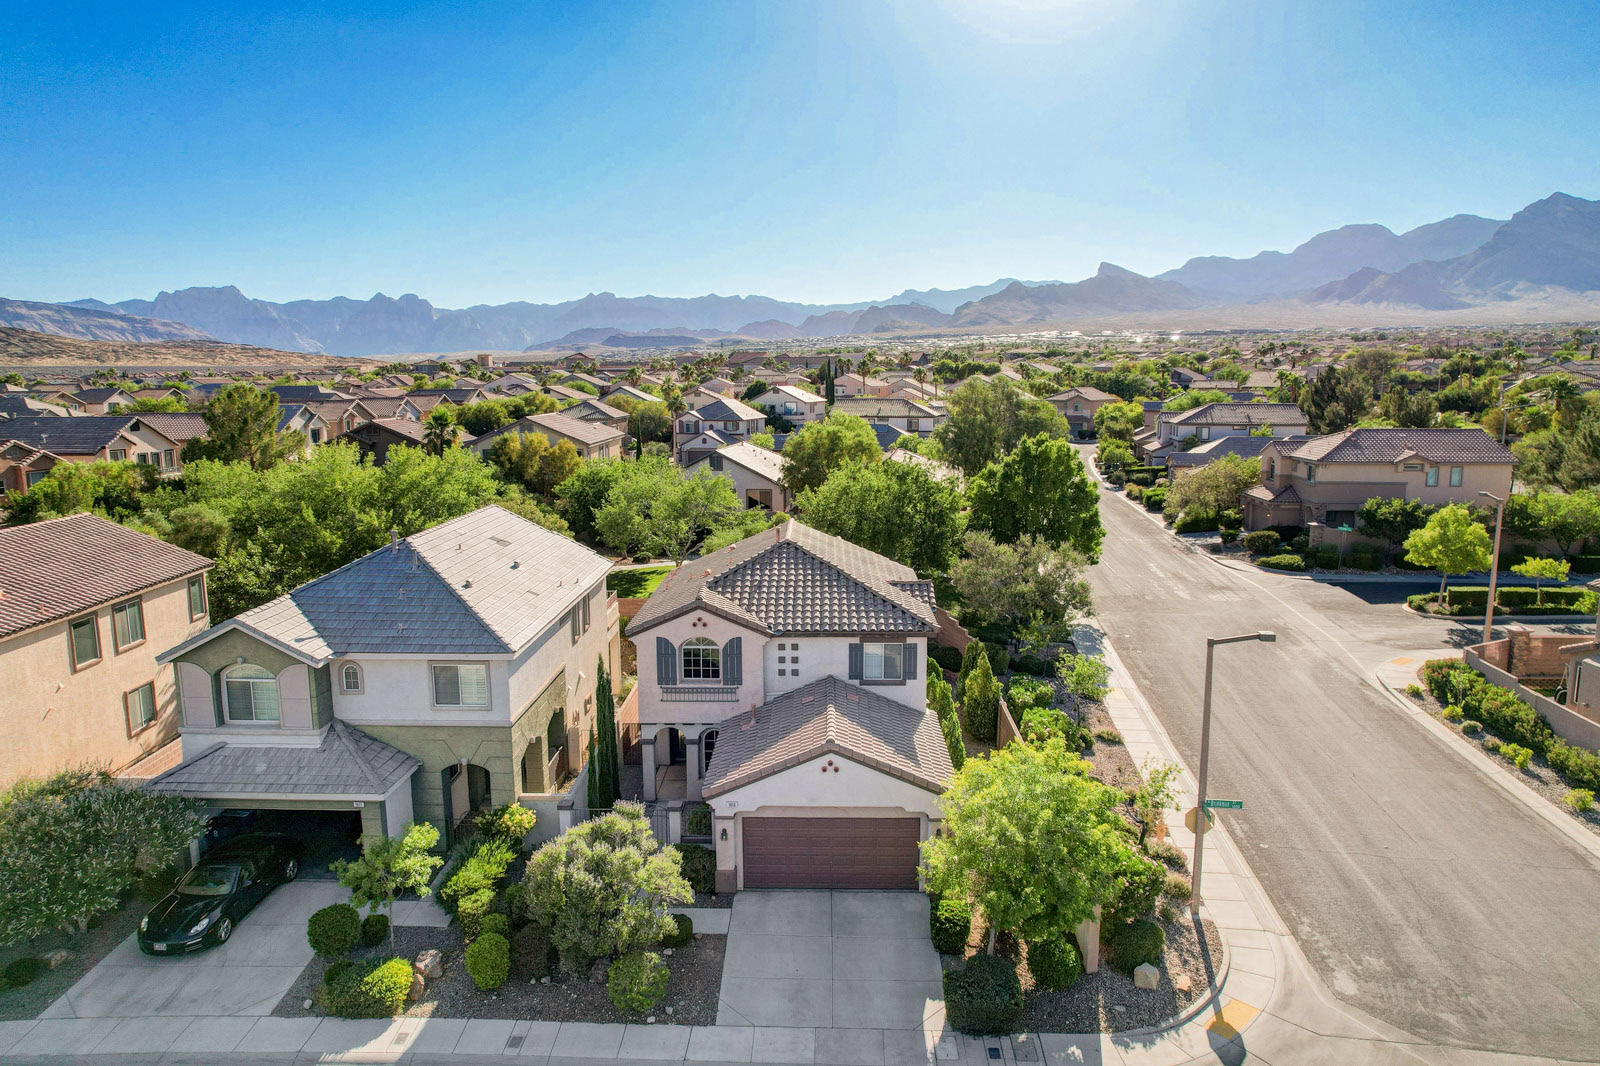
Aerial view of an established Las Vegas residential neighborhood and surrounding mountains
Established neighborhoods across the Las Vegas Valley continue to experience housing demand as the region's population and economy grow.

Will Las Vegas Growth Support the Housing Market Long Term?

Las Vegas’s long-term housing outlook depends on more than tourism, mortgage rates, or one year of home sales. Population growth, employment, healthcare, education, technology, startup activity, industrial development, water planning, and continued reinvestment throughout the Las Vegas Valley all influence whether households and businesses continue choosing Southern Nevada.

Las Vegas remains dependent on tourism, gaming, hospitality, and major events. At the same time, healthcare, professional services, biotechnology, technology, logistics, manufacturing, research, and a growing startup community are giving the regional economy additional depth.

This diversification is real, but it is not complete. Long-term housing demand may benefit from a broader economy, while short-term housing conditions will continue to respond to affordability, employment, mortgage rates, and available supply.

Population Growth Continues to Create a Need for Housing

The UNLV Center for Business and Economic Research projects that Clark County will cross 3 million residents around 2045.

More residents do not guarantee that home prices will rise every year. Population growth does, however, create an ongoing need for houses, apartments, townhomes, condos, schools, medical services, transportation, utilities, and neighborhood infrastructure.

Employment Is Growing Outside Traditional Tourism Sectors

Data from the U.S. Bureau of Labor Statistics showed Las Vegas metropolitan nonfarm employment increasing from the previous year.

Construction, professional and business services, education, healthcare, and other industries contribute to the region’s employment base. Leisure and hospitality remain central, but they no longer tell the entire Las Vegas economic story.

A Southern Nevada Regional Industrial Study identified growth opportunities in healthcare, logistics, business and information technology, manufacturing, gaming, entertainment, and other targeted industries. The same research found that Southern Nevada remains less diversified than several comparable Mountain West metropolitan areas.

A fair reading is that Las Vegas is diversifying and becoming more economically complex, while tourism and hospitality remain particularly important to the region.

Healthcare, Medical Education, and Life Sciences Are Expanding

Healthcare development is becoming a more visible part of the Southern Nevada economy.

Roseman University has opened a four-year medical education program at its Summerlin campus. The university also launched Roseman Bioventures, a 120,000-square-foot life-science incubator designed to provide laboratory space, research support, regulatory guidance, and access to investors for emerging companies.

Developments like these can attract students, physicians, researchers, entrepreneurs, and supporting businesses. Their ultimate housing impact will depend on how successfully the institutions grow, commercialize research, and retain workers in Southern Nevada.

Las Vegas Is Building a Broader Business and Startup Economy

Las Vegas is also gaining recognition for business activity that extends beyond its traditional tourism and gaming economy.

In 2026, Keystone Corporation reported on StartupBlink data showing Las Vegas ranked No. 2 globally for startup community activity from April 2025 through April 2026.

Las Vegas also ranked No. 23 among U.S. startup ecosystems and No. 67 globally in StartupBlink’s broader 2026 Global Startup Ecosystem Index, climbing 17 positions internationally from the prior year. The local startup ecosystem recorded 36.8% growth during the period.

Startup rankings do not directly determine home values, but they are another indication that the Las Vegas economy is becoming more varied. Growth in technology, venture capital, research, healthcare, and entrepreneurship can help attract and retain workers whose employment is not directly tied to the Strip.

Major Investments Continue to Reinforce Las Vegas’s National Profile

Major sports, entertainment, business, and technology investments continue to increase construction activity, national visibility, and private investment in Las Vegas.

Major League Baseball

Athletics Ballpark

Construction is underway on the Athletics’ Las Vegas ballpark, which is scheduled to open for the 2028 Major League Baseball season.

Major Events

Super Bowl and Formula 1

Allegiant Stadium has been selected to host Super Bowl LXIII in 2029. Formula 1 has also extended the Las Vegas Grand Prix through 2037.

Startups & Technology

Startup Activity Is Accelerating

Las Vegas ranked No. 2 globally for startup community activity from April 2025 through April 2026, another sign of Southern Nevada’s growing technology and entrepreneurial ecosystem.
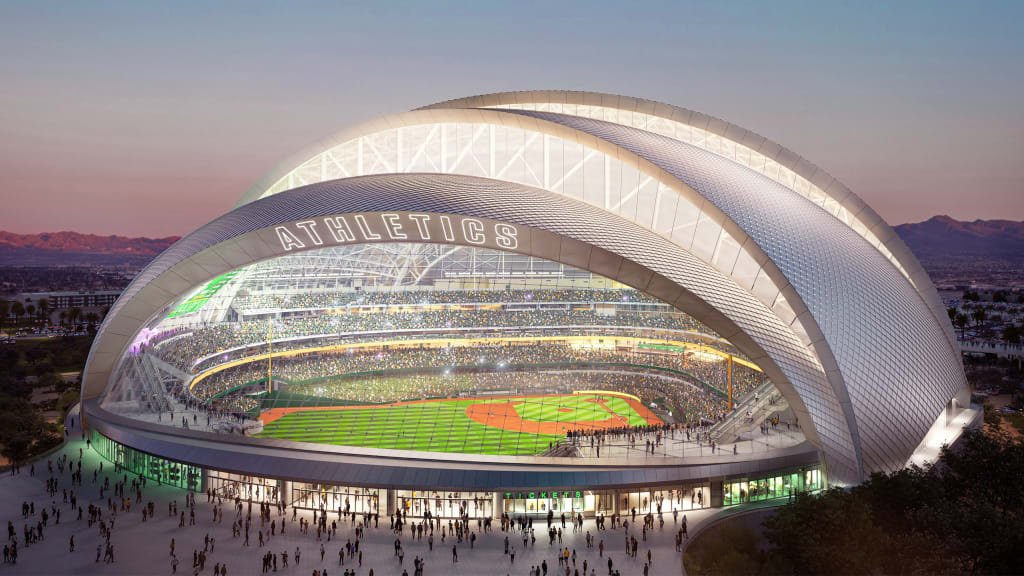
Rendering of the proposed Athletics baseball stadium in Las Vegas, Nevada
Rendering of the proposed Athletics baseball stadium in Las Vegas, Nevada.

Sports and entertainment projects should not be confused with economic diversification on their own. What is more significant for the long-term Las Vegas economy is the combination of continued destination investment with growth in healthcare, research, technology, startups, professional services, logistics, and other industries that can broaden the region’s employment base.

Water Planning Remains Essential to Long-Term Growth

Water is one of the most reasonable questions people ask when considering the long-term growth of a desert city.

The Southern Nevada Water Authority reports that approximately 99% of the water used indoors in its service area is recycled for direct reuse or returned to Lake Mead for return-flow credits.

Return-flow credits allow Southern Nevada to withdraw an additional gallon from the Colorado River for each gallon of treated indoor water returned to the river, while keeping net consumptive use within the region’s allocation.

This is a sophisticated and efficient system, but it does not eliminate long-term Colorado River risk. Conservation, infrastructure investment, regional agreements, and responsible land-use planning remain important to Southern Nevada’s future.

Las Vegas is also producing new water and climate research. WAVR Technologies is working to commercialize atmospheric water-harvesting technology developed at UNLV. WAVR is an interesting example of local innovation, but the developing technology is not currently the foundation of Southern Nevada’s water supply.

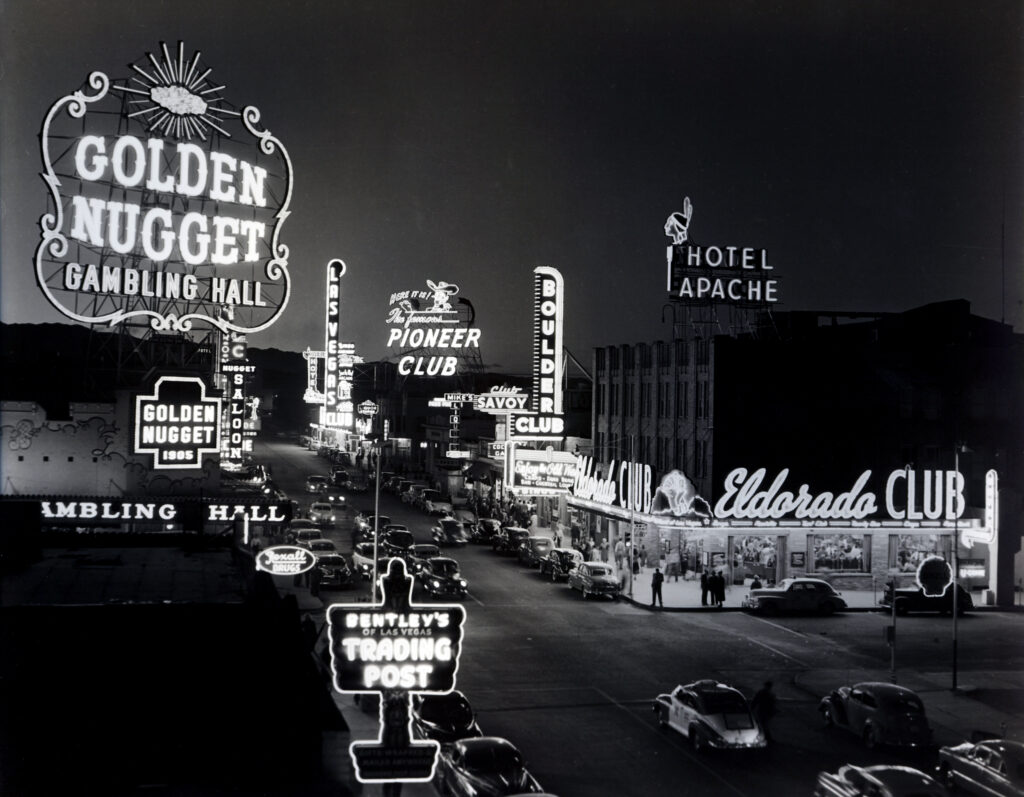
Las Vegas Has Always Been a City of Change

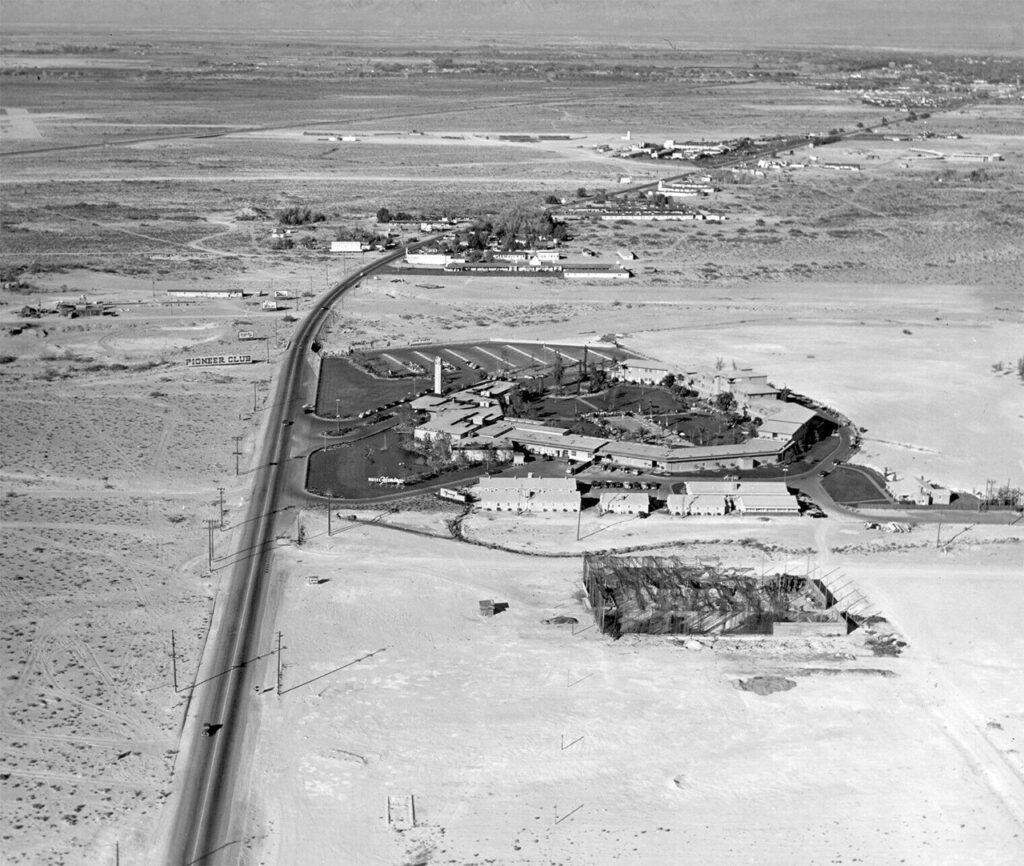
The modern Las Vegas housing market developed alongside decades of population growth, construction, redevelopment, and economic change. The city was transforming long before the housing boom of the early 2000s or the pandemic migration surge.

These historical photographs provide perspective on how dramatically Las Vegas has evolved and how quickly yesterday’s edge of town can become part of an established metropolitan area.
Advice Is Always Free
See if renting your home makes sense.
Image link

How Did the Las Vegas Housing Market Get Here?

Understanding the current Las Vegas housing market requires looking beyond the pandemic.

Over more than two decades, Las Vegas experienced an extraordinary housing boom, a devastating collapse, a long recovery, the pandemic housing surge, and then a sharp increase in financing costs. Each period shaped the housing supply, ownership patterns, and price levels that exist today.

Early 2000s to 2006

The Las Vegas Housing Boom

Las Vegas experienced explosive population growth and homebuilding during the early 2000s.

Housing demand was supported by population growth, easy mortgage credit, speculative purchases, rapid construction, and the belief that Las Vegas real estate prices would continue rising.

Investors and homeowners frequently purchased properties with minimal down payments and financing structures that depended on future appreciation. New communities expanded across the valley, and housing became an increasingly important part of the local economy.

The median price of an existing Southern Nevada single-family home reached approximately $315,000 in June 2006. At the time, that price represented the peak of the local housing boom.

2007 to 2012

The Great Recession and Housing Collapse

When credit conditions tightened and home prices stopped rising, Las Vegas became one of the hardest-hit housing markets in the country.

Foreclosures increased, construction slowed, homeowners lost equity, and distressed properties entered the market in large numbers.

The median price of an existing Southern Nevada single-family home fell from approximately $315,000 in June 2006 to approximately $118,000 in January 2012.

That decline of more than 60% remains central to how many longtime Las Vegas residents view the housing market. The experience created a lasting concern that any future slowdown could become another collapse.

The crisis also changed the region’s future supply. Homebuilding slowed substantially, construction workers left the industry, development projects were postponed, and lenders became more cautious.

2012 to 2019

A Long Recovery From an Unusually Low Bottom

The Las Vegas housing recovery began from an unusually low starting point.

Individual investors, cash buyers, and institutional investment companies purchased distressed homes, repaired many of them, and converted a substantial number into long-term rentals.

As foreclosures were absorbed and the economy improved, prices rose steadily. By January 2019, the median price of an existing Southern Nevada single-family home had returned to approximately $300,000.

That remained slightly below the previous $315,000 peak, but it represented a remarkable recovery from the $118,000 bottom recorded seven years earlier.

The pre-pandemic market was no longer distressed. It was healthier, more expensive, and increasingly constrained by limited production of entry-level housing.

2020 to Early 2022

The Pandemic Housing Surge

The pandemic introduced a very different combination of market forces.

Mortgage rates fell to historic lows. Remote work gave some households greater freedom to relocate. Buyers sought larger homes, home offices, yards, and additional space.

Migration toward Sun Belt markets increased, and Las Vegas remained relatively affordable compared with many coastal metropolitan areas.

At the same time, relatively few homeowners wanted to sell during the earliest period of pandemic uncertainty. New construction could not immediately respond to the increase in demand, and many single-family homes were already retained as rentals.

The result was extreme competition. The median price of an existing Southern Nevada single-family home reached a then-record $482,000 in May 2022.

Mid-2022

Mortgage Rates Changed the Market Quickly

The Federal Reserve began raising interest rates in response to inflation, and mortgage rates increased rapidly.

The monthly payment required to purchase the same home rose dramatically, even when the asking price did not change. Many buyers lost purchasing power, and some withdrew from the market.

Sales slowed, inventory increased, and the Las Vegas median single-family price declined from its May 2022 peak of $482,000 to approximately $425,000 by December 2022.

That correction was meaningful, but it did not return prices to their pre-pandemic level. It also did not produce the widespread distressed-sale conditions experienced during the Great Recession.

2023 to 2026

High Prices Meet High Financing Costs

The defining tension of the post-pandemic Las Vegas housing market has been the combination of elevated home prices and elevated mortgage rates.

Buyers faced larger monthly payments, while many existing homeowners had mortgages with rates far below prevailing market rates. This discouraged some owners from selling and reduced normal housing turnover.

At the same time, substantial homeowner equity, cash ownership, and investor-held properties gave many owners the ability to wait rather than sell under pressure. That financial flexibility helped reduce the number of forced sales even as transaction activity slowed.

Prices did not continue rising at the pandemic pace, and some measurements showed periods of flattening or modest decline. However, overall Las Vegas home values remained materially above their pre-pandemic baseline.

The S&P Cotality Case-Shiller Las Vegas Home Price Index remained near 299 in April 2026, with January 2000 established as an index value of 100.

That does not mean every Las Vegas property tripled in value. It does show how substantially the broader market changed over the first quarter of this century.

Historical median-price references are drawn from reports published by Las Vegas REALTORS, formerly the Greater Las Vegas Association of REALTORS. The January 2019 historical report discusses the 2006 peak, the 2012 bottom, and the recovery through 2019.

How Institutional Investors Changed the Las Vegas Housing Supply

Investor ownership remains an important part of the Las Vegas housing story, but not all investors are the same.

The term “investor” can describe everyone from a homeowner renting a former residence to a small landlord, a family purchasing a second property, or a large institutional owner controlling thousands of homes.

Both individual and institutional investors purchased large numbers of Las Vegas homes after the Great Recession. Many of those properties remain in the rental market rather than returning to the for-sale inventory.

This reduced the number of entry-level houses available for purchase in some neighborhoods, but it also created rental housing for households that want or need to live in a house without purchasing one.
Historical map showing institutional investor ownership in Las Vegas neighborhoods
Institutional investors accumulated single-family homes in several Las Vegas neighborhoods following the Great Recession. This earlier map is included for historical context and does not represent the exact distribution of institutional ownership in 2026.

Build-to-rent communities have since added another category. These are neighborhoods constructed specifically for rental occupancy instead of existing homes removed from the resale market.

Investor activity should be tracked carefully, but it should not be treated as the sole explanation for housing affordability. Mortgage rates, household incomes, land availability, construction costs, zoning, population growth, and the production of entry-level homes also influence prices.

Why Have Las Vegas Home Prices Stayed Elevated?

Several long-term forces have helped keep Las Vegas home prices above their pre-pandemic levels:

  • The region entered the pandemic after years of limited entry-level housing production.
  • Population growth continued creating new household demand.
  • Historically low mortgage rates increased purchasing power during 2020 and 2021.
  • Out-of-state migration brought additional buyers into Southern Nevada.
  • Individual and institutional investors retained many houses as long-term rentals.
  • Low mortgage rates, substantial homeowner equity, and cash ownership reduced the number of owners under immediate pressure to sell.
  • Construction, labor, land, and material costs made new housing more expensive to produce.
  • Higher mortgage rates reduced affordability without creating an immediate wave of forced sales.

These factors do not guarantee that prices will rise every year. They help explain why the market did not simply return to its 2019 price level when mortgage rates increased.

A housing market can remain healthy without rising every month. It can become slower, more balanced, and more negotiable without becoming distressed.

Advice Is Always Free
Established in 2010. Rice Real Estate & Property Management
Image link

What Indicators Matter Most in the Las Vegas Housing Market?

No single statistic explains the Las Vegas real estate market. The clearest picture comes from watching supply, demand, financing, pricing, and transaction behavior together.

Housing Supply and Demand

  • Active housing inventory
  • New listings
  • Closed home sales
  • Months of available supply
  • Pending sales

Pricing and Negotiation

  • Median sale price
  • Days on market
  • Total listing-to-closing time
  • Price reductions
  • Seller concessions
  • Appraisal gaps

Financing and Affordability

  • Mortgage interest rates
  • Monthly payment affordability
  • Builder financing incentives
  • Insurance and HOA costs
  • Household income growth

Seller and Distress Indicators

  • Withdrawn listings
  • Employment and unemployment
  • Foreclosures and short sales
  • Forced versus discretionary sales
  • New-home construction

Inventory without sales data can be misleading, just as sales without inventory can be misleading. Transaction behavior can also reveal a changing market before broader median-price statistics fully reflect it.

Rice Real Estate & Property Management Perspective

The Las Vegas housing market has become slower and more negotiable, but we do not view that as unhealthy. Buyers have more choices and more leverage, while sellers need realistic pricing, patience, and greater flexibility on terms.

One of the biggest differences between today's market and the Great Recession is the financial position of many owners. Low-rate mortgages, substantial equity, cash ownership, investor-held homes, and the ability of some homeowners to hold or rent rather than sell reduce the number of owners under pressure to sell immediately.

In our experience, sellers who understand that a complete sale may take several months and who price according to current buyer behavior can still have a successful sale. The market is slower, but still functioning normally.

Sources and Methodology

Rice Real Estate & Property Management compiled this Las Vegas housing market analysis using single-family inventory, closed-sales activity, months-of-supply calculations, historical housing data, and firsthand observations from Las Vegas and Henderson.

Transaction examples, buyer and seller behavior, appraisal observations, seller concessions, and listing-to-closing timelines identified as Rice Real Estate & Property Management observations are based on firsthand local experience and should not be interpreted as valley-wide statistical averages.

Historical pricing, economic, population, employment, housing, water, startup, and regional development information is drawn from public data, research, and reporting that includes:

Housing markets are local and can change quickly. Valley-wide statistics should not be interpreted as an appraisal, valuation, or guaranteed prediction for an individual property. Historical results do not guarantee future price movement.

External Citation: Heidi Rice’s Las Vegas housing-market analysis has been cited by GOBankingRates and syndicated by Yahoo Finance in national real estate coverage.


Heidi Rice
Heidi Rice
NV Broker and Property Manager
www.ricelasvegas.com/about/

Heidi Rice is the broker and lead property manager at Rice Real Estate & Property Management, serving owners of long-term residential rental properties throughout the Las Vegas Valley, with a primary focus on detached single-family rental homes.